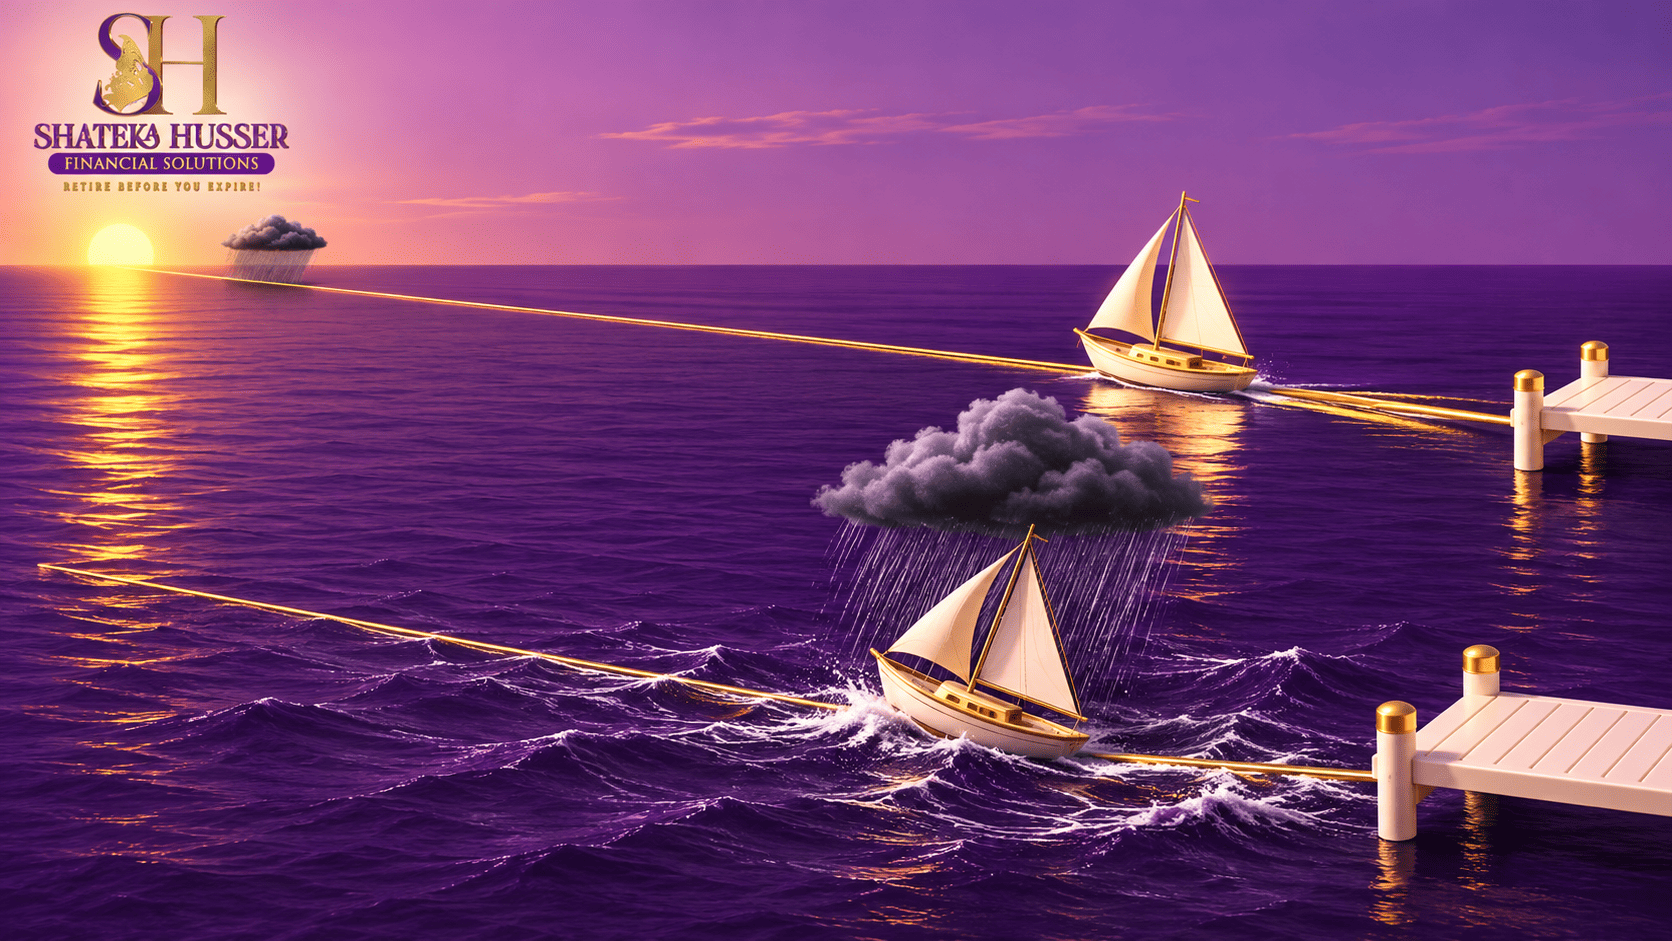
Two people retire at 65, each with $750,000. They own the same investments, take the same withdrawals and, over five years, earn the exact same average return. Five years later, one of them has about $81,000 more than the other.
Same savings. Same returns. Different retirement. The difference isn’t how much they saved. It’s when the losses showed up.
The retirement risk most people never hear about
During your working years, your paycheck replenishes your resources. A market drop hurts, but you’re still adding money and have time to recover.
Retirement changes that relationship. Your savings may now be responsible for replacing the paycheck, and every withdrawal decides how much remains for tomorrow. When the market falls while you’re withdrawing, you have to sell more shares to get the same income. Those shares are gone, and they can’t take part in the recovery.
This is called sequence of returns risk: the risk that the order of your investment returns, not just the average, decides how long your money lasts. It matters most right after withdrawals begin, when your balance is usually at its largest.
A side-by-side example
Hypothetical illustration for education only. It is not a projection of any investment and does not predict or guarantee future results.
Both retirees start with $750,000 and withdraw $40,000 at the beginning of each year, before that year’s return. They earn the same five annual returns, in opposite order. Withdrawals stay fixed for these five years to isolate the effect of timing, and taxes, fees and other income are not included.
| Year | Retiree A (losses first) | Retiree B (gains first) |
|---|---|---|
| 1 | −15% | +20% |
| 2 | −10% | +15% |
| 3 | +8% | +8% |
| 4 | +15% | −10% |
| 5 | +20% | −15% |
| Balance after 5 years | $593,040 | $673,858 |
Both earned an average of 3.6% a year. That’s the simple arithmetic average. Their compound annual growth rate, which measures how money actually grows over time, was also identical at about 2.7%. With no withdrawals at all, both would have ended at exactly $855,117.
The only difference is timing. Retiree A was selling during the losses, so fewer dollars were left to recover. After five years, A has $80,818 less: money that could have supported more income, healthcare costs, travel or a surviving spouse.
That gap doesn’t close on its own. Now suppose both earn an identical 5% a year from year six on, with withdrawals rising 3% a year for inflation from the start (still taken at the beginning of each year, with no taxes or fees). Retiree A can no longer cover a full year’s withdrawal at about age 84. Retiree B reaches that point at about age 86.
Why the first five years carry so much weight
- Your balance is at its largest, so the same percentage loss costs the most dollars.
- Withdrawals can’t wait. The bills keep coming whether or not the market has recovered.
- Inflation keeps pushing costs up, so you may need to withdraw more even in a down year.
- Selling at the wrong time. Without other income or cash on hand, you may have to sell investments while prices are low.
Sequence risk can strike at any point while you’re withdrawing, but early losses tend to leave the longest-lasting mark. That’s why the plan needs to be in place before your first withdrawal, not after the first bad year.
How retirement positioning reduces the risk
You can’t control when the market falls. You can control how your money is positioned when it does. That starts with three questions every retiree should be able to answer.
1. Income: where will your monthly paycheck come from?
Know how much of your monthly needs is covered by income that doesn’t depend on the market, such as Social Security, a pension or other guaranteed sources. When you claim Social Security changes how much your savings must carry in the early years.
2. Protection: what happens to your income if the market drops?
A cash reserve for near-term spending can help you avoid selling during a decline. Money you’ll need in the next few years usually shouldn’t carry the same risk as money you won’t touch for 15 years. Some strategies, including certain annuities, are designed to provide income that doesn’t fall with the market. They come with trade-offs, costs and limits on access, and they aren’t right for everyone.
3. Longevity: will your money last 25 to 30 years or longer?
Match each dollar to its job: income for now, reserves for the next few years and growth for later. Then test whether the plan still works if you live well into your 90s.
No single product solves sequence risk. The right mix depends on your income needs, other assets, health and goals.
Retirement is a position, not a date
Many people treat retirement as the day the paychecks stop. But retirement is not an age. It is an income.
Having a retirement account and having a retirement income plan are two different things. The account shows how much you’ve accumulated. The plan shows how that money will pay you, month after month, through good markets and bad ones.
Your next step
If you’re within a few years of retirement, or already there, a Wealth Clarity Call is your opportunity to see whether your current strategy is positioned to deliver the income, protection and flexibility you expect. Together, we can identify potential gaps, talk through your concerns and decide which planning opportunities deserve a closer look.
Schedule your Wealth Clarity Call
Not ready for a one-on-one conversation? Join our complimentary Executive Retirement Briefing to learn how retirement income, asset positioning and protection work together.
Reserve your seat at the Executive Retirement Briefing
This article is for educational purposes only and is not individual investment, tax or legal advice. The illustration is hypothetical, uses assumed returns and withdrawals, and does not represent any specific investment. Past performance does not guarantee future results. Annuity guarantees depend on the claims-paying ability of the issuing insurance company. Shateka Husser Financial Solutions offers insurance and annuity products; this article is not a recommendation to buy or sell any product.